Contingency fee — you pay nothing unless we recover funds.

COLORADO COVERAGE LAWYERS INSURANCE COVERAGE & BAD FAITH TRIAL COUNSEL

What we handle

Practice areas

Five closely related fights, all of which begin with the same document: the policy your insurer wrote and you paid for.

01

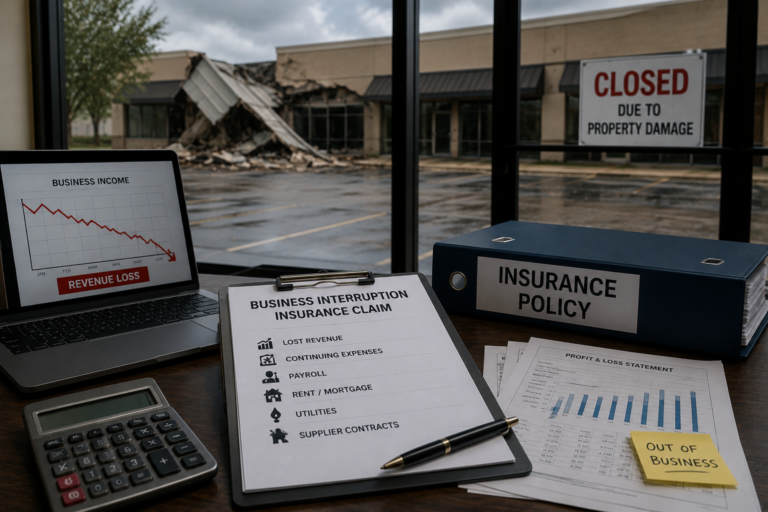
Business Interruption Claims

Lost income and extra expense after a shutdown.

  • Lost net income and continuing expenses
  • Extra expense and expediting costs
  • Civil authority and ingress/egress coverage
Read more
02

Insurance Bad Faith

Unreasonable delay and denial under C.R.S. 10-3-1115.

  • C.R.S. §§ 10-3-1115 and 10-3-1116 claims
  • Common-law bad faith and breach of contract
  • Claims-handling and reserve discovery
Read more
03

Commercial Property Damage

Hail, wind, fire, water and collapse losses.

  • Hail and wind damage to roofs and envelopes
  • Fire, smoke and water losses
  • Matching, code upgrade and depreciation fights
Read more
04

Denied & Underpaid Claims

Reversing a wrongful denial or a lowball payment.

  • Reversing wrongful denials
  • Challenging lowball estimates and scope
  • Reservation of rights and coverage counsel
Read more
05

Policy Review & Coverage Opinions

A written read of what your policy actually covers.

  • Line-by-line reading of the whole policy
  • Written coverage opinion where useful
  • Endorsement and exclusion mapping
Read more

Where they overlap

Most files are two of these at once

A denied hail claim is a property damage case and a denial case. Add three months of silence and it becomes a bad faith case as well. Pick whichever description fits — we will sort out the labels.

Your operation stopped and the revenue stopped with it

Start with business interruption. The questions are whether the shutdown was triggered by a covered cause of loss, how long the period of restoration runs, and what the income calculation should include. If the insurer has already said no, the denial and bad faith analyses run alongside it.

Two minutes, five questions

Is your claim worth a second opinion?

This is not legal advice and it is not a substitute for reading your policy. It is the same short triage our intake lawyers run before they book a call.

Claim strength check

Question 1 of 5

Indicative result

0%

No fee unless we recover

Schedule your free policy review today.

Send us the policy and the letter your insurer sent. We will read both and tell you honestly what we see — at no cost and with no obligation.