Colorado insurance coverage and business interruption lawyers
When an insurer denies, delays or underpays a legitimate claim, the policy is only half the fight. We are Denver trial lawyers who read policies for a living and try coverage cases for a living.
Every commercial insurance policy is unique and needs to be read by a Colorado coverage
specialist. Ours is the reading that is free.
Why we exist
Your insurer should not be the only voice deciding whether you are covered
An adjuster works for the company that wrote the policy. That is not a conspiracy — it is a job
description. But it does mean the first reading of your policy, the one that produces the denial
letter or the low estimate, is done by someone with an interest in the answer.
Ogborn Mihm and Denver Trial Lawyers have spent decades on the other side of that reading. We
combined our coverage practices so Colorado businesses and families could get a second opinion
from lawyers who actually try these cases.
We read the whole policy. Endorsements change the base form
more often than not, and that is usually where the answer is hiding.
We build the number. Forensic accountants and independent
estimators, engaged early, not after the insurer has anchored the file.
We are trial lawyers. Insurers price a file differently when
the firm on the other side has taken coverage cases to verdict.
This is not legal advice and it is not a substitute for reading your policy. It is the
same short triage our intake lawyers run before they book a call.
Businesses that carry the loss while the policy is argued about
Interruption losses land hardest on operations with fixed overhead and revenue that
cannot be deferred. These are the files we see most.
Restaurants & Bars
Hospitality carries thin margins and long leases. A month of closure is rarely a month of loss — it is a season of it.
Medical & Dental Practices
Elective procedures stop, overhead does not. Business income coverage was written for exactly this gap.
Retail & Casinos
Anchor closures, inventory loss and civil-authority orders all touch different sections of the same policy.
Gyms & Fitness Studios
Membership revenue is recurring, which makes the loss easy to prove — if the calculation is done properly.
Theaters & Music Venues
Cancelled runs, deposits, and contingent losses from a supplier or landlord's damage.
Hotels & Lodging
Occupancy losses, contingent business interruption and extra expense for relocation of guests.
How it works
From your first email to a resolved claim
No intake script, no call centre. The first person who reads your file is a lawyer
who could end up trying it.
1
You send us the paperwork
The declarations page, the full policy with endorsements, and anything the insurer has put in
writing. If you do not have the complete policy, we will help you demand it — you are entitled to it.
2
A lawyer reads it — all of it
Not a checklist, not a paralegal summary. We map the coverage grants, the exclusions, the
exceptions that pull coverage back in, and the conditions that carry deadlines.
3
We tell you what we actually think
Including when the answer is no. A clear explanation of why a claim will not work is worth more
than an expensive year finding out the hard way.
4
We build the loss before we argue it
Forensic accounting for income losses, independent estimating for property losses. Insurers
settle numbers they cannot credibly dispute.
5
Negotiation, appraisal, or trial
Most files resolve short of a courtroom. They resolve because the insurer can see that we are
prepared to be in one, and because our trial lawyers have been.
A denial letter is the start of the conversation, not the end of it.
What insurers say
Six sentences we read every week — and what they usually mean
None of these is automatically wrong. All of them are worth testing against the actual
policy language before you accept them.
“
“There was no direct physical loss or damage.”
This is the single most litigated phrase in first-party coverage. Most policies never define it, and Colorado courts have repeatedly found that loss of use or functionality can qualify. The answer lives in your specific wording, not in the adjuster's summary of it.
“
“That is excluded by the wear-and-tear provision.”
Exclusions are read narrowly and the insurer carries the burden of proving one applies. Where a covered peril and an excluded cause combine, Colorado's efficient proximate cause analysis often preserves coverage.
“
“Your loss is below the deductible after depreciation.”
Depreciation is where a great many underpayments hide. Depreciating labor, applying it to code-required upgrades, or refusing to release holdback once repairs are done are all worth challenging.
“
“You did not comply with a policy condition.”
Late notice, a missing sworn proof of loss or a skipped examination under oath only defeat a claim where the insurer can show actual prejudice. That is a real burden, and it is frequently not met.
“
“We need more documents before we can decide.”
An open-ended document request is not an investigation. Colorado's statutory framework requires a reasonable basis for delay, and a request that never ends starts to look like one.
“
“This is our final offer.”
Final until it is not. A large share of the recoveries in coverage disputes arrive after an appraisal demand, a well-supported lawyer's letter, or a filed complaint changes the arithmetic.
Our attorneys
The lawyers who will read your policy
Thomas Neville
Coverage & Appellate
When lawyers need innovative solutions for difficult legal issues, they call Thomas Neville.
He handles insurance disputes at both the trial and appellate levels and has testified before
the Colorado legislature on the regulation of insurance companies.
A partner at Denver Trial Lawyers for over fifteen years and a past President of the Colorado
Trial Lawyers Association. As the owner of several Colorado businesses himself, he reads a
profit-and-loss statement the way he reads a policy.
Civil authority coverage in Colorado: when a government order triggers your business income policy
A government order closed you down and the damage was to someone else's property. That is the exact scenario civil authority coverage was written for — and the exact scenario insurers fight hardest.
What a Colorado insurance bad faith claim is actually worth
Colorado gives policyholders a statutory remedy that does not require proving the insurer knew it was being unreasonable. Here is what it covers, what it is worth, and how it is proved.
Colorado hail and wind claims: the seven fights that decide the number
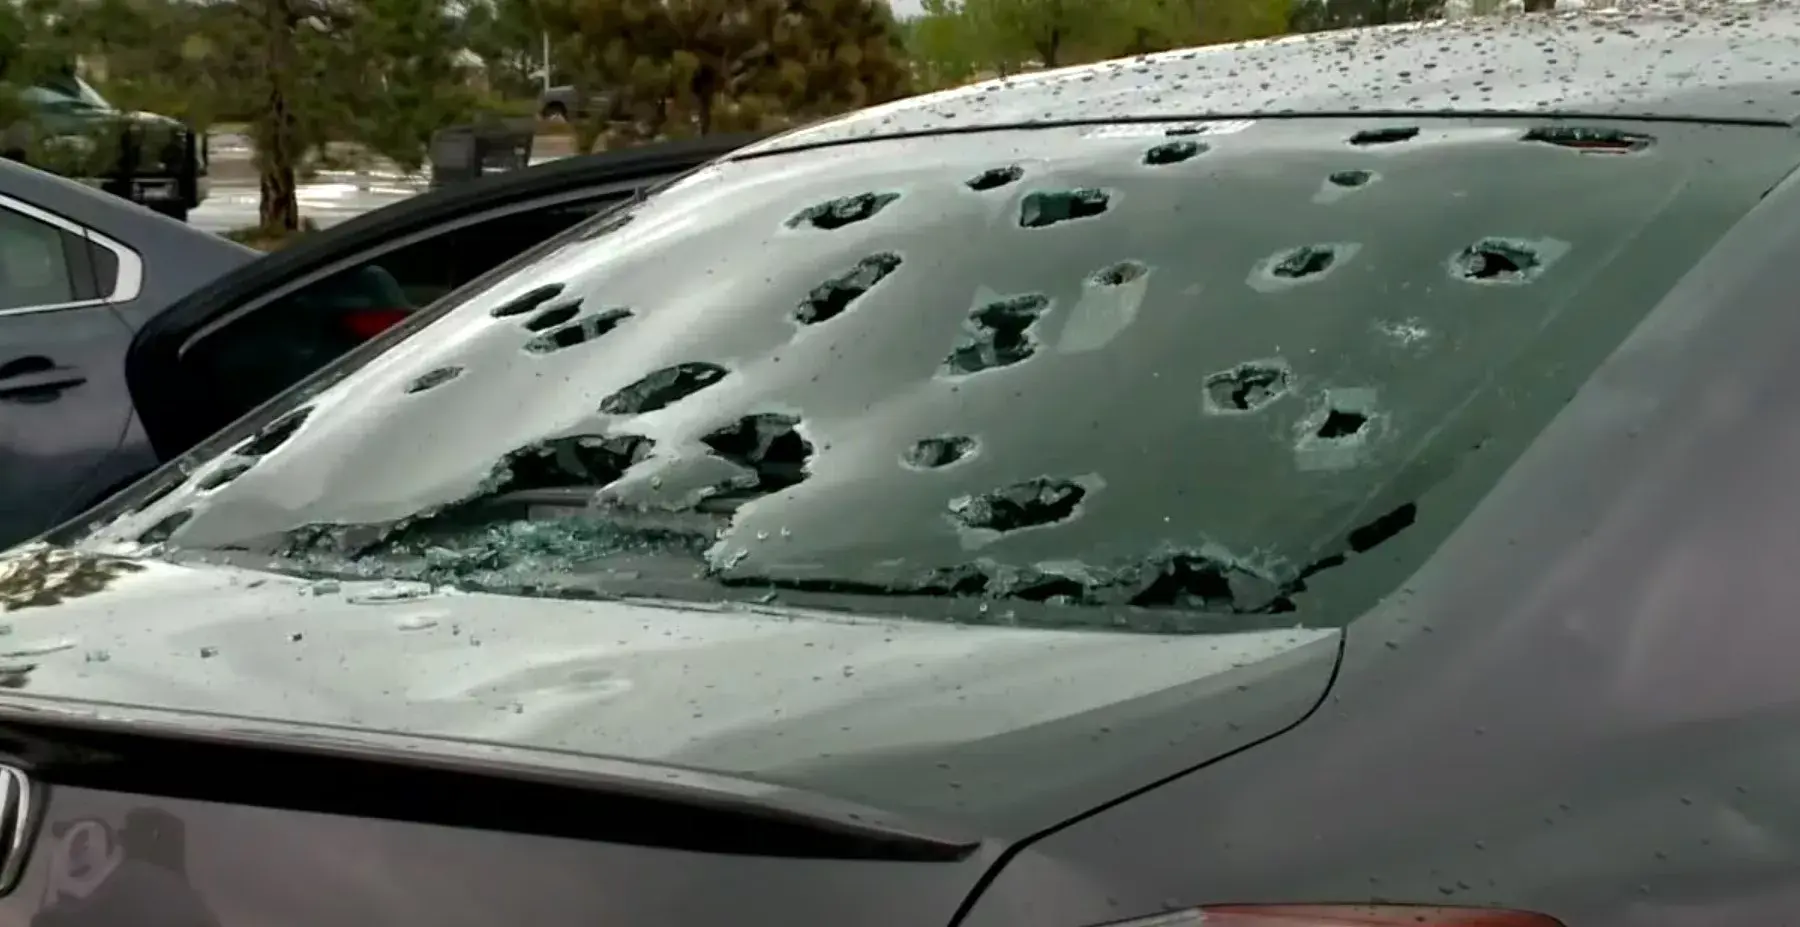
Nobody disputes that the storm happened. The money is decided by seven narrower arguments, and most policyholders never find out they were having six of them.