What a Colorado insurance bad faith claim is actually worth
Colorado gives policyholders a statutory remedy that does not require proving the insurer knew it was being unreasonable. Here is what it covers, what it is worth, and how it is proved.
9 min read Published 2026-01-22 Updated 2026-05-19 Colorado Coverage Lawyers
Most policyholders come to us thinking in terms of one number: the amount the insurer should
have paid. In Colorado that is often the smallest part of the exposure.
Two claims, two standards
Colorado recognises two separate routes when a first-party insurer mishandles a claim, and they have
different elements.
Common-law bad faith
The traditional tort requires the policyholder to show that the insurer's conduct was unreasonable
and that the insurer knew its conduct was unreasonable or recklessly disregarded that fact. It is a
two-part test, and the second part — a state of mind — is what makes it harder.
Statutory unreasonable delay or denial
C.R.S. § 10-3-1115 provides that an insurer shall not unreasonably delay or deny payment of a claim
for benefits owed to a first-party claimant. C.R.S. § 10-3-1116 then gives the claimant a civil action
to recover reasonable attorney fees and court costs and two times the covered benefit.
The critical difference: the statutory claim has no knowledge element. If the delay or denial was
unreasonable, the remedy follows. The policyholder does not have to get inside the adjuster's head.
Both are usually pleaded together
They are not alternatives. The statutory claim is more reliably provable; the common-law claim opens the
door to consequential and, in the right case, exemplary damages. Pleading both preserves the full range.
The statutory claim in detail
Three features of §§ 10-3-1115 and 10-3-1116 shape how these cases are run.
“Delay” is independently actionable. An insurer that eventually pays, but
unreasonably late, has still violated the statute. This is why files that sit for months without a
decision are worth reviewing even after payment arrives.
The fee award runs one way. The statute allows the first-party claimant to recover
reasonable attorney fees and costs. It does not create a mirror-image right for the insurer.
The multiplier attaches to the covered benefit, not to the total damages. Establishing
what the benefit was — and that it was owed — is the analytical centre of the claim.
What counts as a covered benefit
This is more contested than it sounds. A “benefit” is an amount the policy obliged the insurer
to pay. Where the insurer paid part of a claim and unreasonably withheld the rest, the withheld portion is
the benefit for statutory purposes. Where the insurer denied outright, the benefit is what should have been
paid. Where the dispute is about the amount of a partly-paid loss, the covered benefit is the
difference — which is why a properly built independent estimate does double duty in these cases.
What makes conduct unreasonable
Reasonableness is measured against industry standards, and Colorado's legislature has already written down
much of what it regards as unfair. C.R.S. § 10-3-1104(1)(h) lists unfair claim settlement practices,
including:
Misrepresenting pertinent facts or policy provisions relating to coverage
Failing to acknowledge and act reasonably promptly on communications about claims
Failing to adopt and implement reasonable standards for the prompt investigation of claims
Refusing to pay claims without conducting a reasonable investigation based on all available information
Not attempting in good faith to effectuate prompt, fair and equitable settlement of claims in which
liability has become reasonably clear
Compelling insureds to institute litigation to recover amounts due by offering substantially less than
the amounts ultimately recovered
Failing to promptly provide a reasonable explanation of the basis in the policy for a denial or a
compromise offer
An insurer remains entitled to dispute a genuinely debatable claim. The line is crossed when the debate is
manufactured — when the investigation looked only for facts supporting denial, or when the explanation
given cannot survive contact with the policy language it cites.
How the damages stack up
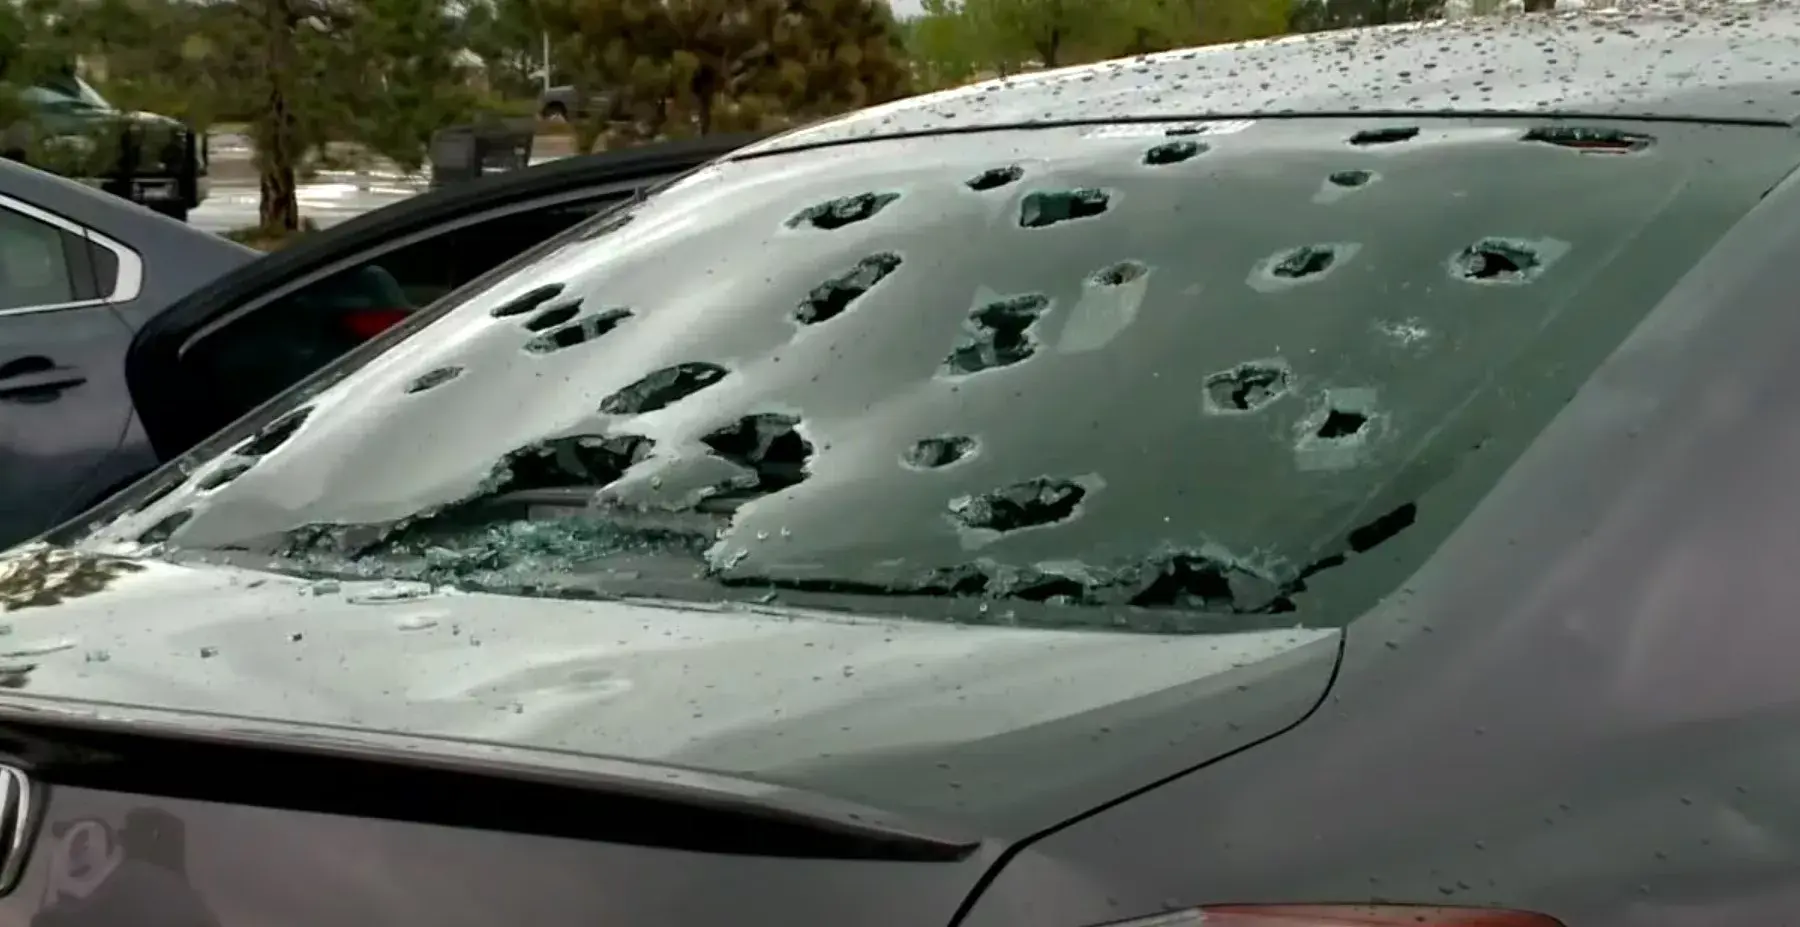
Take a hypothetical commercial hail claim in which the insurer paid $180,000 and the correct figure was
$600,000, with the $420,000 shortfall unreasonably withheld for fourteen months.
Component
Source
Illustrative amount
Unpaid covered benefit
Breach of contract
$420,000
Two times the covered benefit
C.R.S. § 10-3-1116
$840,000
Reasonable attorney fees and costs
C.R.S. § 10-3-1116
Determined by the court
Consequential losses
Common-law bad faith
Fact-dependent
Exemplary damages
C.R.S. § 13-21-102
Only on wilful and wanton conduct
This is an illustration of how the statutory structure works, not a valuation of any real
claim and not a prediction. Every case depends on its own policy, facts and record.
The practical consequence is straightforward: an insurer weighing whether to contest a $420,000 shortfall
is not weighing $420,000. That asymmetry is the leverage the legislature intended to create.
Proving it: inside the claim file
Bad faith cases are won in discovery. The material that matters:
The complete claim file, including the activity log with its timestamps and the
identity of every person who touched the file
Claims-handling manuals, guidelines and training materials — the company's own
statement of the standard it holds itself to
Reserve history, which frequently shows the company's internal view of value diverging
sharply from its offers
Retained expert and engineering reports, including drafts and instructions
Adjuster authority limits, caseloads and performance metrics — the structural
pressures that shaped the handling
Expert testimony from a claims-handling specialist then measures the conduct against industry standards for
the jury. The most powerful moment in many of these trials is not an argument. It is a side-by-side of the
manual and the log.
Building the chronology that wins
The most persuasive exhibit in most bad faith trials is not an expert report. It is a two-column table:
what the insurer's own manual said should happen, and what the activity log shows happened.
You can start building your half of it today, and it costs nothing.
Record
Why it matters later
Date and time of every call, with the name and title of who you spoke to
Establishes who knew what and when; adjuster turnover is a recurring theme in delayed files
What was promised, in their words
Unkept commitments are the clearest evidence of unreasonable delay
Every document request, and the date you complied
Defeats the standard non-cooperation defence before it is raised
Every document you requested and did not receive
Failing to provide a reasonable explanation of a denial is itself a listed unfair practice
Gaps — periods where nothing at all happened
Silence is the substance of a delay claim; a table of empty weeks is more eloquent than argument
Business consequences as they occur
Consequential damages under the common-law claim have to be evidenced contemporaneously
Send a short written summary to the adjuster periodically confirming your understanding of where the claim
stands. It is a courtesy, it is often useful, and it converts your record into a record the insurer has
received and not corrected.
First-party and third-party bad faith are different
The phrase “bad faith” covers two distinct situations, and confusing them leads people to the
wrong analysis.
First-party
Your own insurer refuses to pay you a benefit under your own policy: the denied hail claim, the withheld
business income, the underpaid contents loss. This is where C.R.S. §§ 10-3-1115 and 10-3-1116
operate, and it is the bulk of our practice.
Third-party
Your liability insurer mishandles the defence or settlement of a claim someone has brought against you
— refusing a reasonable settlement within limits and exposing you personally to an excess judgment.
The duties there arise from the insurer's control of the defence, and the analysis and remedies differ.
Both are serious. Only the first carries the statutory multiplier, which is why the distinction matters
from the first conversation.
What weakens an otherwise strong claim
Inconsistent numbers. A sworn proof of loss at one figure, a
public adjuster's estimate at another and a demand letter at a third invites the argument that nobody
knew what the loss was — which makes any delay look reasonable.
Unanswered requests. Even unreasonable document requests
should be answered, in writing, on the record. Silence hands the insurer its best defence.
Emotional correspondence. Understandable, and it will be
read aloud. Keep the file factual.
Letting the contractual deadline run. A time-barred
contract claim complicates everything that sits on top of it.
Settling the benefit without reserving the rest. Read what
you sign. Broad releases signed for a partial payment are the single most common way a viable statutory
claim disappears.
The defences insurers raise
Defence
Substance
Where it usually fails
Genuine dispute
The claim was fairly debatable
Where the investigation was one-sided or the cited provision does not say what the letter claims
Advice of counsel
The denial followed a coverage opinion
Raising it can waive privilege over the opinion and its factual basis
Policyholder non-cooperation
Documents or an examination were not provided
Where the requests were open-ended, or the insurer cannot show prejudice
No covered benefit
Nothing was owed, so nothing was delayed
Merges with the coverage case; if the benefit is established the defence collapses
Timing and deadlines
Statutory bad faith claims and contract claims run on different clocks, and your policy's suit limitation
clause may be shorter than either. A common and expensive mistake is to let a two-year contractual deadline
pass while a claim is being negotiated in apparent good faith. Negotiation does not toll a limitation period
unless the insurer has agreed in writing that it does.
Keep a chronology from day one
Date, time, who you spoke to, what they said, what they promised, and what arrived afterwards. Bad faith
is a case about process, and the policyholder's contemporaneous record of the process is frequently the most
credible document in the trial.
This guide is general information, not legal advice
Colorado insurance disputes turn on the exact wording of your policy and the facts of your loss.
Nothing here creates an attorney–client relationship. If you want to know what your policy says,
send it — we read it for free.
Civil authority coverage in Colorado: when a government order triggers your business income policy
A government order closed you down and the damage was to someone else's property. That is the exact scenario civil authority coverage was written for — and the exact scenario insurers fight hardest.
Colorado hail and wind claims: the seven fights that decide the number
Nobody disputes that the storm happened. The money is decided by seven narrower arguments, and most policyholders never find out they were having six of them.
 Business income